Solo 401(k) for the Self-Employed: Eligibility, Limits and Best Providers
A Solo 401(k) lets freelancers and business owners save far more than an IRA. See eligibility, 2026 limits, an example and how to choose a provider.
A Solo 401(k) lets freelancers and business owners save far more than an IRA. See eligibility, 2026 limits, an example and how to choose a provider.
Vesting decides how much of your employer’s 401(k) contributions you keep when you leave. See cliff and graded schedules with clear examples.
You can often borrow up to $50,000 or half your vested 401(k) balance. See how loans work, the repayment rules and the risks before you borrow.
A 401(k) hardship withdrawal lets you tap savings for urgent needs, but taxes and penalties apply. See who qualifies, the rules and the alternatives.
Rolling over a 401(k) to an IRA doesn’t have to be taxable or complicated. Follow these steps, avoid common mistakes and keep your money growing.
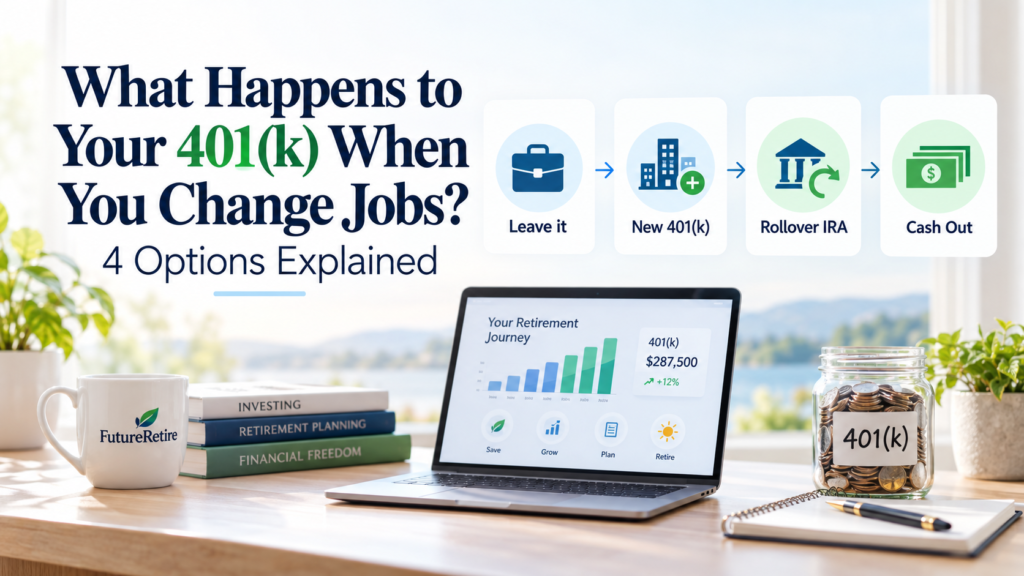
Leaving a job? You have four choices for your old 401(k): leave it, roll it over, move it to a new plan or cash out. Here’s how to decide.
Traditional 401(k) saves taxes now; Roth saves taxes later. Compare the differences, see examples and learn which fits your situation.
A 401(k) match is free money from your employer. Learn how matching formulas work, see real examples, and avoid mistakes that cost you thousands.
Last reviewed: 7/10/2026 · Reviewed by: David E. Quick answer: For 2026, you can contribute up to $24,500 to your […]
Last reviewed: 7/10/2026 · Reviewed by: David E. The short answer: Contribute at least enough to earn your employer’s full […]