Traditional vs Roth 401(k): Which Is Better for You?
Traditional 401(k) saves taxes now; Roth saves taxes later. Compare the differences, see examples and learn which fits your situation.
A 401(k) is an employer-sponsored retirement account. Contributions, employer matching, investment choices and withdrawal rules can affect how the account fits into a retirement plan. Use this guide library to understand the rules, compare options and find the next article for your situation.
Begin with the amount you can contribute and how your plan works. Employee deferrals, employer contributions and catch-up rules have different limits.
Traditional and Roth contributions have different tax treatment. A Roth 401(k) is also different from a Roth IRA, and eligibility rules vary by account.
Before moving or withdrawing savings, compare plan features and tax consequences. A rollover, loan and hardship withdrawal are different transactions.
Use our 401(k) growth calculator to see how contributions, matching and hypothetical returns affect a projection. Then explore the Roth IRA and IRA guide library for related account rules. Tools and articles are educational and do not provide personalized advice or guaranteed results.
Traditional 401(k) saves taxes now; Roth saves taxes later. Compare the differences, see examples and learn which fits your situation.
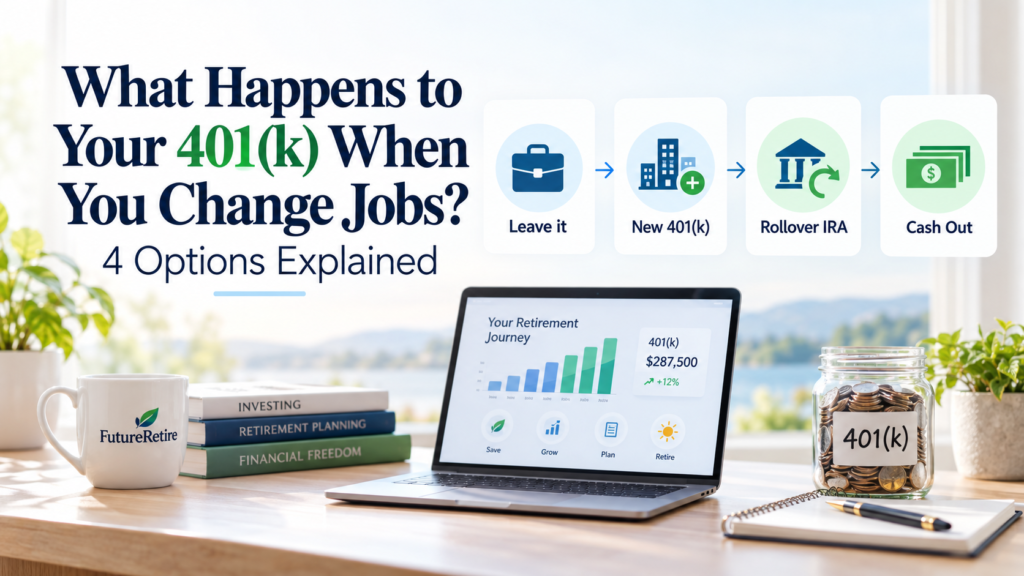
Leaving a job? You have four choices for your old 401(k): leave it, roll it over, move it to a new plan or cash out. Here’s how to decide.
Rolling over a 401(k) to an IRA doesn’t have to be taxable or complicated. Follow these steps, avoid common mistakes and keep your money growing.
A 401(k) hardship withdrawal lets you tap savings for urgent needs, but taxes and penalties apply. See who qualifies, the rules and the alternatives.
You can often borrow up to $50,000 or half your vested 401(k) balance. See how loans work, the repayment rules and the risks before you borrow.
Vesting decides how much of your employer’s 401(k) contributions you keep when you leave. See cliff and graded schedules with clear examples.
A Solo 401(k) lets freelancers and business owners save far more than an IRA. See eligibility, 2026 limits, an example and how to choose a provider.
Compare 401(k) providers for small businesses by cost, features and ease of setup, plus tax credits that can cover startup costs.
403(b) and 401(k) plans share the same limits but differ in who can use them, investments and fees. See the key differences and what to check in yours.
A 401(k) match is free money from your employer. Learn how matching formulas work, see real examples, and avoid mistakes that cost you thousands.